


 PDF Version Demo
Help you relieve the burden
With Financial-Accounting-Reporting test guide, you only need a small bag to hold everything you need to learn. In order to make the learning time of the students more flexible, Financial-Accounting-Reporting exam materials specially launched APP, PDF, and PC three modes. With the APP mode, you can download all the learning information to your mobile phone. In this way, whether you are in the subway, on the road, or even shopping, you can take out your mobile phone for review. Financial-Accounting-Reporting study guide materials also offer a PDF mode that allows you to print the data onto paper so that you can take notes as you like and help you to memorize your knowledge.
Financial-Accounting-Reporting exam certification is one of the most important certification recently. When qualified by the Financial-Accounting-Reporting certification, you will get a good job easily with high salary. Besides, the career opportunities will be open for a certified person. Now, you can get the valid and best useful Financial-Accounting-Reporting exam training material. Financial-Accounting-Reporting will help you to strengthen your technical knowledge and allow you pass at your first try.
Accurately predict test questions
The industry experts hired by Financial-Accounting-Reporting exam materials are those who have been engaged in the research of Financial-Accounting-Reporting exam for many years. They have a keen sense of smell in the direction of the exam. Therefore, they can make accurate predictions on the exam questions. Therefore, our study materials specifically introduce a mock examination function. With Financial-Accounting-Reporting exam materials, you can not only feel the real exam environment, but also experience the difficulty of the exam. You can test your true level through simulated exams. At the same time, after repeated practice of Financial-Accounting-Reporting study guide materials, I believe that you will feel familiar with these questions during the exam and you will feel that taking the exam is as easy as doing exercises in peace. According to our statistics on the data so far, the passing rate of the students who have purchased one exam exceeds 99%, which is enough to see that Financial-Accounting-Reporting test guide is a high-quality product that can help you to realize your dream.
You can learn immediately after payment
You will receive Financial-Accounting-Reporting exam materials immediately after your payment is successful, and then, you can use Financial-Accounting-Reporting test guide to learn. Everyone knows that time is very important and hopes to learn efficiently, especially for those who have taken a lot of detours and wasted a lot of time. Once they discover Financial-Accounting-Reporting study guide materials, they will definitely want to seize the time to learn. However, students often purchase materials from the Internet, who always encounters a problem that they have to waste several days of time on transportation, especially for those students who live in remote areas. But with Financial-Accounting-Reporting exam materials, there is no way for you to waste time. The sooner you download and use Financial-Accounting-Reporting study guide materials, the sooner you get the certificate.
Admission Test Financial-Accounting-Reporting Exam Syllabus Topics:
| Section | Objectives |
|---|---|
| Equity, Investments, and Business Combinations | - Bonds and debt instruments - Stockholders' equity - Business combinations and consolidations |
| Financial Statements and Transactions | - Balance sheet and statement of cash flows - Revenue recognition (ASC 606) - Income statement and comprehensive income |
| Assets and Liabilities Accounting | - Leases (ASC 842) - Fixed assets and intangible assets - Liabilities and contingencies - Cash, receivables, and inventory |
| Governmental and Not-for-Profit Accounting | - Not-for-profit financial reporting - Governmental fund accounting |
| Specialized Accounting Topics | - Accounting changes and error corrections - Foreign currency transactions - Pensions and post-employment benefits |
| Conceptual Framework and Financial Reporting | - Disclosure requirements - FASB conceptual framework - Financial statement presentation |
Admission Test Certified Public Accountant (Financial Accounting & Reporting) Sample Questions:
Question #1
Kell Corp.'s $95,000 net income for the quarter ended September 30, 1990, included the following aftertax items:
* A $60,000 extraordinary gain, realized on April 30, 1990, was allocated equally to the second, third, and fourth quarters of 1990.
* A $16,000 cumulative-effect loss resulting from a change in inventory valuation method was recognized on August 2, 1990.
In addition, Kell paid $48,000 on February 1, 1990, for 1990 calendar-year property taxes. Of this amount, $12,000 was allocated to the third quarter of 1990.
For the quarter ended September 30, 1990, Kell should report net income of:
A. $91,000
B. $111,000
C. $103,000
D. $115,000
Question #2
On January 2, 1993, Quo, Inc. hired Reed to be its controller. During the year, Reed, working closely with Quo's president and outside accountants, made changes in accounting policies, corrected several errors dating from 1992 and before, and instituted new accounting policies.
Quo's 1993 financial statements will be presented in comparative form with its 1992 financial statements.
This question represents one of Quo's transactions. List B represents the general accounting treatment required for these transactions. These treatments are:
* Cumulative effect approach - Include the cumulative effect of the adjustment resulting from the accounting change or error correction in the 1993 financial statements, and do not restate the 1992 financial statements.
* Retroactive or retrospective restatement approach - Restate the 1992 financial statements and adjust 1992 beginning retained earnings if the error or change affects a period prior to 1992.
* Prospective approach - Report 1993 and future financial statements on the new basis but do not restate 1992 financial statements.
Item to Be Answered
The equipment that Quo manufactures is sold with a five-year warranty. Because of a production breakthrough, Quo reduced its computation of warranty costs from 3% of sales to 1% of sales.
List B (Select one)
A. Prospective approach.
B. Retroactive or retrospective restatement approach.
C. Cumulative effect approach.
Question #3
Which of the following should be disclosed in a summary of significant accounting policies?
I. Management's intention to maintain or vary the dividend payout ratio.
II. Criteria for determining which investments are treated as cash equivalents.
III. Composition of the sales order backlog by segment.
A. I and III.
B. I only.
C. II and III.
D. II only.
Question #4
Dean Co. acquired 100% of Morey Corp. prior to 1989. During 1989, the individual companies included in their financial statements the following: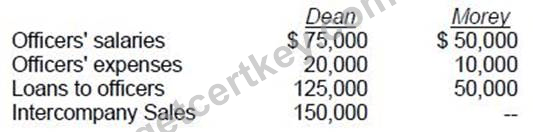
What amount should be reported as related party disclosures in the notes to Dean's 1989 consolidated financial statements?
A. $175,000
B. $150,000
C. $330,000
D. $155,000
Question #5
On December 31, 20X2, the Board of Directors of Maxy Manufacturing, Inc. committed to a plan to discontinue the operations of its Alpha division. Maxy estimated that Alpha's 20X3 operating loss would be $500,000 and that the fair value of Alpha's facilities was $300,000 less than their carrying amounts.
Alpha's 20X2 operating loss was $1,400,000, and the division was actually sold for $400,000 less than its carrying amount in 20X3. Maxy's effective tax rate is 30%.
In its 20X2 income statement, what amount should Maxy report as loss from discontinued operations?
A. $1,190,000
B. $1,700,000
C. $1,400,000
D. $980,000
Solutions:
| Question #1 Correct Answer: A | Question #2 Correct Answer: A | Question #3 Correct Answer: D | Question #4 Correct Answer: A | Question #5 Correct Answer: A |
 1381 Customer Reviews


 Quality and ValueGetCertKey Practice Exams are written to the highest standards of technical accuracy, using only certified subject matter experts and published authors for development - no all study materials.
 Tested and ApprovedWe are committed to the process of vendor and third party approvals. We believe professionals and executives alike deserve the confidence of quality coverage these authorizations provide.
 Easy to PassIf you prepare for the exams using our GetCertKey testing engine, It is easy to succeed for all certifications in the first attempt. You don't have to deal with all dumps or any free torrent / rapidshare all stuff.
 Try Before BuyGetCertKey offers free demo of each product. You can check out the interface, question quality and usability of our practice exams before you decide to buy.
